Move-up and relocation guide
Buying and selling at the same time: how to move up (or move to Toronto) without the stress
Selling one home while buying the next is like changing lanes on the highway: very doable, as long as you check your mirrors and signal early. This guide shows you how to choose what comes first, how bridge financing works, how to line up your closing dates and how to make moving day feel easy.
By Spiro Vrysellas, Broker, Vrysellas Team, Elevate Realty Inc., Brokerage.
The plan at a glance
Tap any section to jump to it. You are running two transactions that depend on each other, so the order you do things in matters as much as the price you get.
- 1Buy first or sell first?
- 2Bridge financing
- 3Line up closing dates
- 4Offers conditional on sale
- 5Your two-track timeline
- 6Know your equity
- 7Moving logistics
- 8Relocating to Toronto
Section oneBuy first or sell first?
This is the big decision, and there is no single right answer. It comes down to one question: which risk would you rather manage? Buying first risks owning two homes for a while. Selling first risks having nowhere to go.
- You can take your time to find the right home
- No pressure to settle or rent in between
- One move, straight into the new place
- You may need to sell on a deadline
- You must be able to carry or bridge both
- You know exactly how much equity you have
- Your budget for the next home is certain
- No risk of owning two homes
- Pressure to find a home before your sale closes
- You may need a short rental or storage
Quick decision helper
Each statement that is true for you leans you one way. If most lean one direction, that is probably your answer. Then we confirm it together with your real numbers.
Homes like yours are selling quickly in your area right now.
The home you want is rare: a specific street, school or layout.
You have strong equity and a lender is happy to approve bridge financing.
Your current home is unusual and could take a while to sell.
You could not carry two homes, even for a short time.
You need to know your exact budget before you shop.
Pro tip: there is a middle path. Get your home completely ready to list (repairs, paint, photos) before you start shopping. When you find the right place, you can list within days instead of weeks, which shrinks the risk on both sides.
Section twoBridge financing, explained simply
Say your new home closes on the 1st and your current home closes on the 10th. Your down payment is tied up in the home you have not sold yet. Bridge financing is a short-term loan from your lender that "bridges" those days: it lends you your own equity early, then gets paid back the day your sale closes.
A firm sale on your current home (not just a listing), a mortgage approval on the new one and enough equity to cover the bridge. Lenders typically only bridge for a short window.
Interest for the days you use it plus a lender or legal fee. For a short gap it is often a small price for a stress-free move. Ask your mortgage broker for an exact quote.
Bridge financing is not available from every lender and the terms vary, so bring it up with your mortgage broker at the very start, not the week before closing.
Watch out: if you buy first and have not sold yet, you cannot get bridge financing until your sale is firm. Without a sale, you would need to qualify to carry both mortgages, or have another source of funds ready.
Section threeLining up your closing dates
The closing date is when ownership and money change hands. When you buy and sell, you are choosing how your two closing dates sit next to each other. There are three ways to do it:
Sale closes in the morning, purchase in the afternoon. No bridge needed, but one delayed wire or late lawyer can leave the moving truck waiting in the driveway.
Our favourite when the numbers work. You get the keys, paint and clean, then move calmly. A short bridge covers the gap.
No bridge, no carrying two homes. You may need a short rental, a stay with family or storage in between.
The longer the gap, the more it costs. A few days to a couple of weeks is the sweet spot for most move-up buyers.
Pro tip: if you can, avoid closing on the very last business day of the month or right before a long weekend. Lawyers, lenders and movers are at their busiest, and there is less room to fix a hiccup.
Section fourOffers conditional on the sale of your home
A conditional offer says: "I will buy your home, but only if I sell mine by a certain date." It protects you from owning two homes. The catch is that sellers usually do not love it.
Why sellers dislike them
The seller's home is effectively on hold while your home is on the market. If your sale falls through, they start over, often weeks later. In a busy market with other buyers ready to go firm, a sale condition can push your offer to the bottom of the pile, or lose it entirely on an offer date.
How sellers protect themselves
When sellers do accept a sale condition, they often add an escape clause. They keep marketing the home, and if another buyer makes a firm offer, you get a short window to remove your condition and go firm, or step aside.
- A slower market with fewer buyers
- A home that has been listed for a while
- Your home is priced right and ready to list now
- Offer dates with several bidders
- Popular streets where homes sell fast
- Your home is not listed or ready yet
Section fiveYour two-track timeline
Think of it as two trains on parallel tracks. Each has its own stops, and the job is to have them arrive at the same station within days of each other. Here is how the two tracks typically run when you buy first:
- Prep, repairs and photos
- List and show
- Firm sale
- Sale closes
- Pre-approval and bridge plan
- Strategy and tours
- Firm purchase
- Purchase closes
Example only. The order of each track stays the same; the timing depends on your plan.
- Get your equity estimate and pre-approval (with a bridge plan) before anything else
- Prepare your home to list before you start touring
- Choose your purchase closing date with your sale timing in mind
- List right after you buy, priced to sell within your window
- Set the sale closing a few days after the purchase closing
Section sixHow much equity will you really have?
Your equity is what is left after the sale, and it becomes most of your next down payment. It is never simply "sale price minus mortgage". Here is the real formula:
The surprise for many sellers is the mortgage penalty. If you break a fixed-rate mortgage early, it can be significant. Ask your lender two questions now: what would the penalty be, and can I port my mortgage to the new home instead? Porting can sometimes avoid the penalty altogether.
Plug your own numbers into our proceeds of sale calculator to see what you will walk away with.
Section sevenMoving logistics
The best transaction in the world can still end with a chaotic moving day. A little planning goes a long way:
- Book movers as soon as your dates are firm, especially near the end of the month
- Moving out of or into a condo? Book the service elevator and ask about move fees or deposits
- Remember keys are usually released in the afternoon on closing day
- Transfer utilities, home insurance and internet, and set up mail forwarding
- Pack a "first night" box: chargers, toiletries, bedding, kettle, snacks
Pro tip: with a few days of overlap, you can paint, clean and do small jobs in an empty house. It is the single biggest stress saver for families with kids or pets.
Section eightRelocating to Toronto from elsewhere
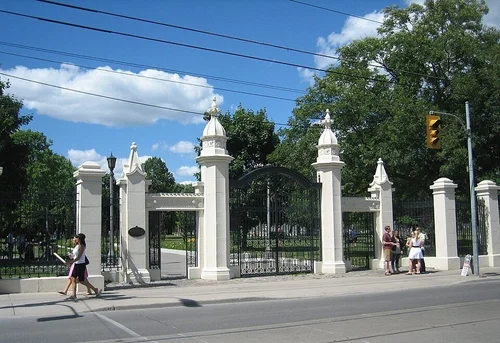
Moving to Toronto from another city, province or country adds one more challenge: you do not know the streets yet. The goal is to learn the city fast, so you choose a neighbourhood with confidence and not just a listing.
Learn the neighbourhoods first
Toronto is a city of very different neighbourhoods, sometimes changing block by block. Start with how you want to live: walk to cafés and parks like Trinity Bellwoods, family streets near Corso Italia and the shops on St. Clair West, the village feel of Roncesvalles, or a downtown condo close to work. Our Toronto real estate guides are a good place to begin.
Use virtual tours, then visit in person
Live video walkthroughs let you see a home before you fly in, and we can point the camera at the things listing photos skip: the basement, the street, the neighbours' yards. Then plan a focused trip with a shortlist ready, so every hour on the ground counts.
Pre-approval sorted, neighbourhoods narrowed, a shortlist reviewed by video, inspections ready to book.
Walk the streets at different times of day, tour the shortlist, and be ready to make an offer if the right home is there.
Watch out: moving from outside Canada? There can be extra rules and taxes for buyers who are not Canadian citizens or permanent residents, and lenders may need extra documents for new income. Speak with a lawyer and a mortgage broker before you start looking.
How our team runs both sides
When you buy and sell with the same team, nothing falls between the cracks. Spiro and a full team coordinate your listing and your purchase as one plan: pricing and preparing your home to sell within your window, negotiating your purchase closing with your sale in mind, and keeping your mortgage broker and lawyer in the loop on every date.
- Dates chosen without seeing the other side
- Nobody watching the bridge timing
- Surprises in the final week
- Both closing dates set on purpose
- Lender and lawyer briefed from day one
- Moving day you can actually plan
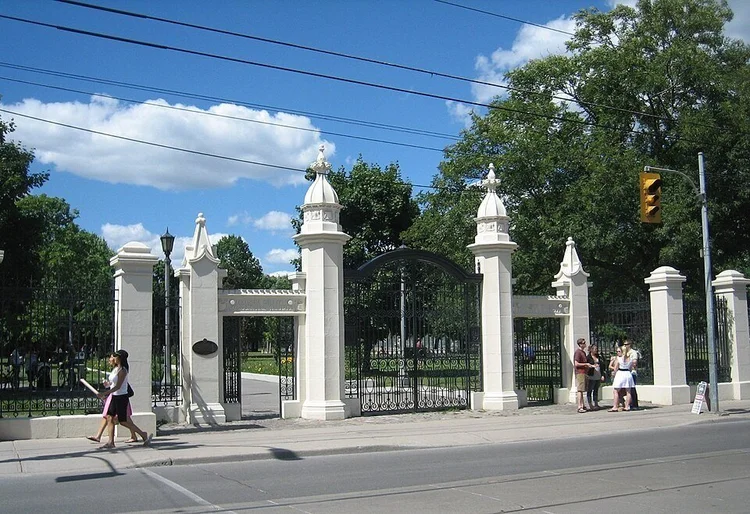
How Nina and Theo moved from a condo to a semi near Trinity Bellwoods
An example move-up, buying first with a short bridge, using realistic Toronto numbers.
- Before shopping: Estimated their equity, got pre-approved with a bridge plan and prepared their downtown condo to list: repairs, paint and photos done.
- Day 0: Bought a semi near Trinity Bellwoods firm at $1,595,000 with a 90-day closing. Sent the $79,750 deposit (5%) from their $85,000 in savings.
- Day 10: Listed the condo.
- Day 24: Condo sold firm for $765,000, with closing set for day 97, one week after their purchase.
- Day 90: Purchase closed. A one-week bridge loan of about $299,800 covered the rest of the down payment and closing costs. They painted and moved in calmly.
- Day 97: Condo sale closed and the bridge loan was repaid from the sale.
| Their numbers | Amount |
|---|---|
| Condo sale price | $765,000 |
| Mortgage paid off | $418,000 |
| Commission and HST (example) | $43,222 |
| Legal fees and mortgage discharge (example) | $4,000 |
| Equity from the sale | $299,778 |
| Semi purchase price | $1,595,000 |
| Down payment (20%) | $319,000 |
| Ontario land transfer tax | $28,375 |
| Toronto land transfer tax | $28,375 |
| Legal fees, bridge fee and moving | about $5,900 |
| Cash needed for the purchase | about $381,650 |
| Topped up from savings | about $81,872 |
| New mortgage | $1,276,000 |
Example only. Nina and Theo are not real clients. Commission, legal, bridge and moving costs are illustrative, and land transfer tax uses the brackets in place when this guide was written. As previous owners they did not qualify for first-time buyer rebates. Your numbers will differ.
Your buy-and-sell checklist
- Get a realistic estimate of your home's value and your equity
- Ask your lender about prepayment penalties and porting
- Get pre-approved, including a bridge financing plan
- Decide buy first or sell first with your real numbers
- Prepare your home to list before you start touring
- Set closing dates a few days apart, away from month-end if possible
- Book movers, elevators and utility transfers as soon as dates are firm
Frequently asked questions
Is it better to buy first or sell first?
It depends on your market, your home and your finances. Buying first makes sense when homes like yours sell quickly and you have the equity to bridge. Selling first makes sense when your home could take time to sell or you cannot carry two homes. Many people prepare their home to list before shopping, which reduces the risk either way.
What is bridge financing?
A short-term loan from your lender that lets you use the equity in your current home before it closes. It covers the gap when your purchase closes before your sale, and is repaid when your sale closes. You usually need a firm sale to qualify.
Can I make an offer conditional on selling my home?
Yes, but sellers often dislike it because it puts their home on hold. It works best in slower markets or on homes that have been listed for a while. Sellers commonly add an escape clause that lets them keep marketing and gives you a short window to go firm if another offer comes in.
How many days apart should my closing dates be?
For many move-up buyers, a few days to a couple of weeks with the purchase closing first is the sweet spot. It gives you time to paint and move calmly, and keeps the bridge financing cost small. Same-day closings work too, but leave no room for delays.
How do I choose a Toronto neighbourhood if I am moving from out of town?
Start with how you want to live, then learn the neighbourhoods that match. Use video tours to narrow your shortlist, and plan a focused trip to walk the streets and see the best homes in person.
Keep learning
How much will I walk away with when I sell? How much cash do I need to close? Trinity Bellwoods neighbourhood guide All Toronto real estate guidesExample figures are for illustration only. Lender products, bridge financing terms, tax rates and government rules change, so confirm details with your mortgage broker and lawyer. This is not financial or legal advice.